The week’s priorities
4. October slowed overall; Honda’s result was stronger
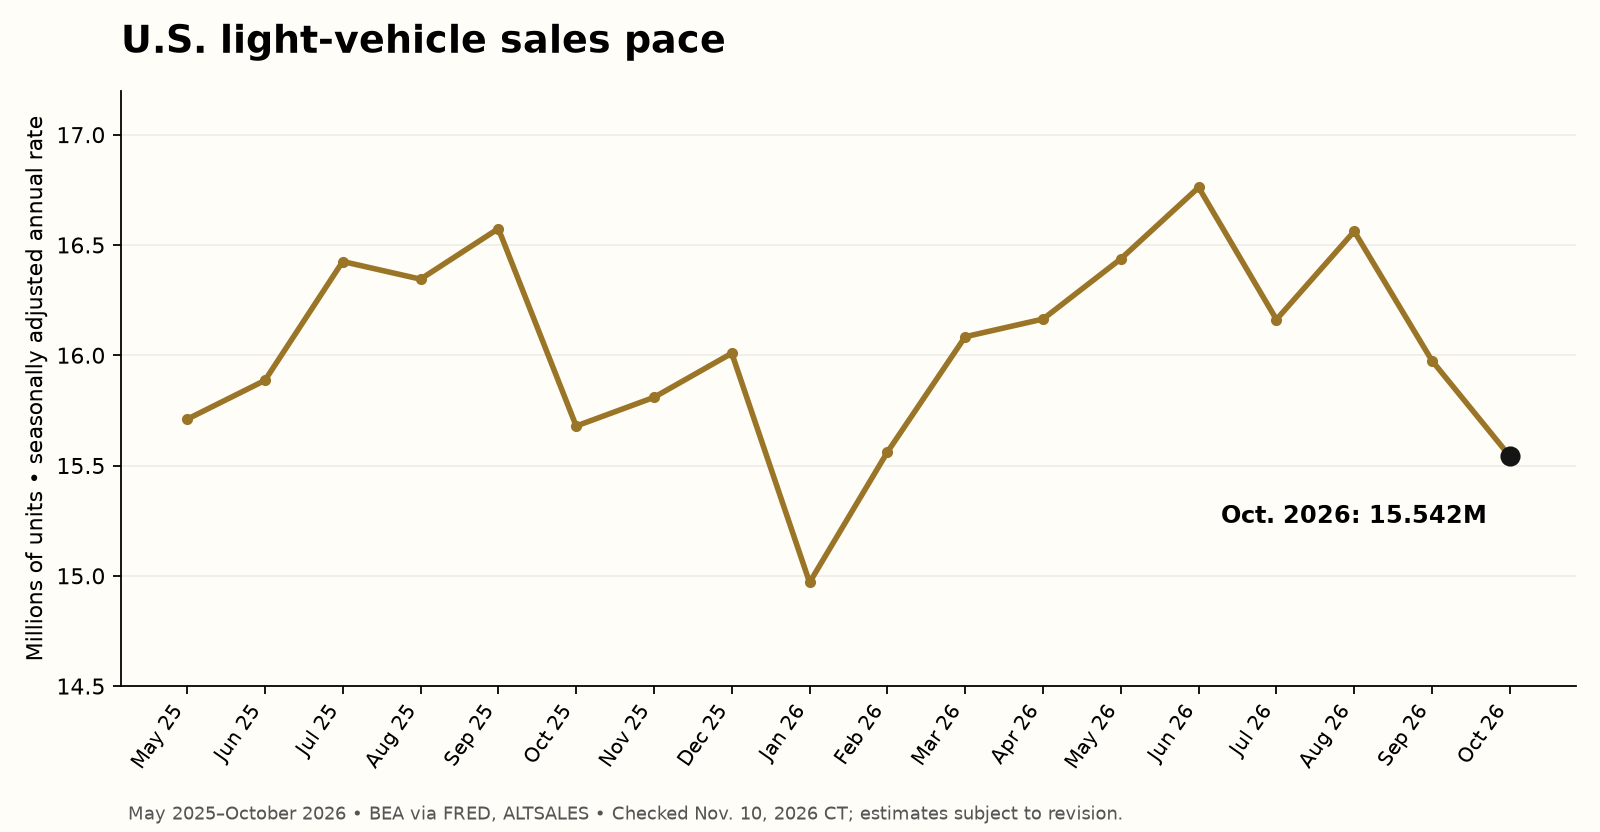
The BEA light-vehicle series, available through FRED, puts October’s U.S. sales pace at 15.542 million, down from 15.975 million in September, on a seasonally adjusted annual basis. Cox’s Nov. 5 initial estimate was 15.5 million, below its earlier 16.1 million forecast. American Honda separately reported 119,952 October sales, up 8%; Honda-brand hybrids reached an October record of 32,519. One strong brand result does not erase a softer market. Inventory and financing plans may need to differ by brand and powertrain rather than assume one market-wide result.
Why it ranks: Sales pace and brand mix shape inventory decisions and the number of financing and protection-product opportunities.
Possible industry effect: Stores may need different plans by brand and powertrain rather than one market-wide assumption. A hybrid sales record alone does not establish higher service-contract or GAP demand.
Sources: BEA via FRED, updated Nov. 6; Cox Automotive, Nov. 5 update; American Honda, Nov. 3.
18 monthly observations; millions of units, seasonally adjusted annual rate. BEA via FRED. Rebuilt with the Nov. 6 data update; estimates remain subject to revision.
The other stories from Saturday, November 7, 2026.
1. The loan-interest deduction needs a careful explanation
The car-loan interest deduction needs a careful explanation. Eligibility rules and financed amounts matter; it is not a $10,000 tax credit.
Read the full summary →
2. Customer consent belongs in the delivery checklist
GM’s driver-data settlement puts customer consent and dealership enrollment controls back on the delivery checklist.
Read the full summary →
3. Group 1’s F&I decline is bigger in total than per deal
Group 1’s total F&I revenue fell more than income per deal. The U.S.-only figure and consolidated figure cover different scopes.
Read the full summary →
5. Product income carries most of JM&A’s F&I mix
Products supplied most F&I income per deal in JM&A’s sample. The participating dealers are not a national census.
Read the full summary →
6. CarMax plans to grow lending and protection income together
CarMax paired Tier 2 lending and protection plans in its growth strategy. The targets are not results already delivered.
Read the full summary →
7. Arch’s PDS agreement puts provider ownership on the watch list
Arch’s agreement to buy PDS puts provider ownership on the watch list. It does not show that current coverage or terms have changed.
Read the full summary →
Tax rule: keep the dates and financed amounts separate
Keep the tax rule’s effective date separate from the deduction’s tax years, and separate eligible financed amounts from other debt.
Read the full summary →
Data settlement: don’t accept permissions for the customer
The GM settlement is not a new industry-wide regulation. Customer enrollment permissions should remain with the customer.
Read the full summary →
Two recall campaigns belong on the VIN check
GM brake software and Hyundai airbag software recalls belong on inventory VIN checks. Safety remedies are not a reason to sell a service contract.
Read the full summary →